
Buy Now or Pay in Installments? A Smart Guide for Indonesian Migrant Workers

15 Jun 2026
Introduction: Should You Pay for Everything Upfront?
You have been working overseas for months, sending money back to Indonesia, and finally your family needs a new refrigerator.
Or perhaps the washing machine has stopped working. The family’s old phone is no longer reliable. The house needs a new television, laptop, air conditioner, or another essential appliance.
The price is Rp6 million.
You have the money sitting in your account.
So, what makes more sense?
Pay the full Rp6 million today — or buy it through installments and keep more of your cash available?
At first, paying in full may seem like the obvious choice. There is no monthly payment to worry about, and the purchase is settled immediately.
But installments can sometimes make sense too, especially when keeping cash available is important.
The smarter question is not simply “cash or installments?”
It is:
“Which option makes more sense for my financial situation?”
Paying in Full vs Installments: What’s the Real Difference?
Let’s use a simple example.
Imagine your family needs a washing machine costing Rp6 million.
Option A: Pay in Full
You pay Rp6 million immediately.
Pros:
- no monthly repayment
- no future installment obligation
- potentially cheaper if there are no additional financing costs
- you own the item without ongoing payments
Cons:
- Rp6 million leaves your savings immediately
- less money remains for emergencies
- a second unexpected expense could put pressure on your finances
Option B: Pay in Installments
Instead of paying everything at once, you divide the purchase into agreed payments.
Pros:
- keep more cash available today
- spread the cost across several months
- easier to manage a large purchase within monthly income
- potentially preserve emergency savings
Cons:
- you have a future payment obligation
- financing may include fees or other costs
- missing payments can create additional problems
- multiple installment purchases can become difficult to manage
The right option depends on the total cost and your ability to repay, not simply how small the monthly payment looks.
The Most Important Question: What Happens to Your Cash After You Buy?
This is where migrant workers need to think differently.
Suppose you have Rp10 million in savings and the appliance costs Rp6 million.
If you pay everything upfront, you are left with:
Rp10 million − Rp6 million = Rp4 million
That may be perfectly fine.
But what happens if your salary is delayed next month?
What if your family suddenly needs Rp2 million for a medical expense?
What if your employer changes your working schedule and your income temporarily falls?
Suddenly, the Rp6 million purchase feels very different.
An installment plan could potentially allow you to keep more cash available for emergencies — provided the total financing cost is reasonable and the repayments fit comfortably within your income.
That is the key distinction.
Installments are not automatically cheaper. They can simply make the timing of your cash outflow easier to manage.
5 Things to Check Before Choosing Installments
Don’t choose an installment plan just because the monthly payment looks affordable.
Check the full picture.
1. What Is the Total Amount You Will Pay?
This is more important than the monthly installment.
For example:
Cash price: Rp6,000,000
Installment: Rp550,000 × 12 months = Rp6,600,000
The difference is Rp600,000.
Now you can decide whether keeping the additional cash available is worth the additional financing cost.
Always compare the total repayment, not just the monthly amount.
2. Are There Additional Fees?
Read the terms carefully.
Depending on the product and provider, there may be costs associated with the financing.
Look for information about:
- interest or financing charges
- administration fees
- late-payment charges
- other applicable costs
OJK’s current BNPL rules require providers to give consumers clear and understandable information, including installment amounts and payment frequency.
If you do not understand a fee, ask before agreeing.
3. Can You Still Afford the Monthly Payment?
This is where many consumers make a mistake.
A Rp500,000 monthly installment may look small.
But what happens if you already have:
- another installment
- a motorcycle payment
- a loan
- rent
- school expenses
- monthly family remittance?
One small installment may be manageable.
Several small installments can become a large monthly obligation.
Before taking another installment plan, calculate your existing commitments.
The question is not “Can I pay this month?”
It is:
“Can I comfortably pay this every month until the financing ends?”
4. Will You Still Have Emergency Savings?
This is particularly important for Indonesian migrant workers.
Your salary may be earned overseas, but your financial responsibilities may exist in two countries.
You may need money for yourself abroad and your family in Indonesia.
Before paying cash for a large household purchase, ask:
“How much money will I have left after buying this?”
If paying upfront leaves your emergency savings dangerously low, preserving some cash may be worth considering.
5. Is the Item Actually Necessary?
Before using installments, ask one final question:
Do I really need this now?
There is a significant difference between:
“Our refrigerator has broken and we need a replacement.”
and
“The refrigerator works, but we want a newer model.”
Financing can be useful for an essential purchase, but using installments for every optional purchase can quickly lead to over-commitment.
A Simple Decision Checklist
Before choosing cash or installments, ask yourself:
Choose Cash When:
- you can pay without hurting your emergency savings
- the purchase price is affordable
- financing would add unnecessary costs
- you want to avoid another monthly obligation
Consider Installments When:
- the purchase is genuinely necessary
- keeping cash available is important
- the total financing cost is reasonable
- the monthly payment comfortably fits your budget
- you have checked your existing debt obligations
Neither option is automatically better.
The better option is the one that fits your financial situation.
BNPL Is a Tool — Not Free Money
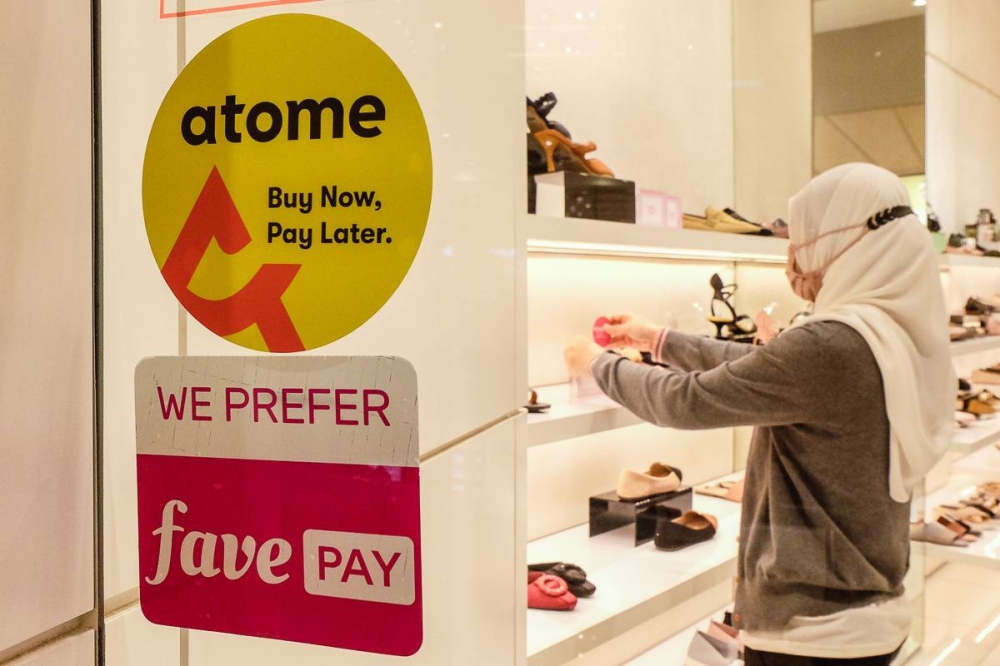
Buy Now, Pay Later can make a large purchase easier to spread across several payments.
But it is still a financial commitment.
OJK issued POJK No. 32 of 2025, effective from December 2025, specifically regulating BNPL and strengthening requirements around prudence, consumer protection, data protection, and clear information disclosure.
In 2026, OJK also introduced further implementation rules covering areas such as eligibility assessment, credit scoring, disclosure, data management, and other consumer-protection requirements.
So before using BNPL, treat it like any other form of financing:
Understand it. Compare it. Budget for it.
Conclusion: Don’t Ask “Cash or Installments?” Ask “Which Is Smarter for Me?”
Buying an important household item for your family is not a bad financial decision.
The real question is how you pay for it.
Before deciding, look beyond the monthly payment.
Check the total cost. Check your existing commitments. Check your emergency savings. And most importantly, check whether the purchase is something your family genuinely needs.
For Indonesian migrant workers, every financial decision should consider both sides of the journey — your life overseas and your family’s life back home.
A smart financial decision is not necessarily the one that costs the least today.
It is the one that leaves you financially stronger tomorrow.